Loan-to-value for non-residents: bank valuation, equity and German mortgage rates
Your loan-to-value ratio affects both the mortgage amount and the interest rate when you live abroad. Income strength and lender choice are especially important, and the range is wider than for residents.
Strong enough income can support borrowing of up to 100 % of the bank’s lending value, including with a foreign-currency salary. Purchase costs must come from your own funds.
What loan-to-value do non-residents actually get on a German mortgage?
A loan-to-value of up to 100 % can be reached where the income is strong enough. The range runs from 60 to 100 % depending on income type and creditworthiness, and the basis is the bank's valuation. Plan equity of up to 40 % plus purchase costs of roughly 8 to 15 %, which this calculation assumes are paid from equity.
This is not a blanket ban: individual lenders may finance purchase costs for applicants with very strong creditworthiness. KfW 124 can also cover eligible purchase costs for qualifying owner-occupied homes.
Eligibility, affordability and approval still need to be checked.
What determines your loan-to-value ratio?
Up to 100 % of the lending value is achievable within a range of 60–100 %, depending on income type and creditworthiness. The basis is the bank's valuation, not the purchase price.
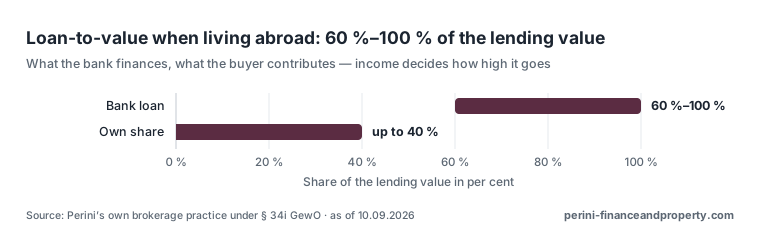
Living abroad does not automatically mean a lower loan-to-value. German banks lend to tax non-residents at 60 % to 100 % of the lending value — the own share is correspondingly up to 40 %. What pushes the range upwards is not a missing own share but a high, documentable income; income in a foreign currency expressly counts.
The purchase costs come from own funds in every case — a purchase with no own funds at all is not what is meant.
The reference is the bank's lending value, not the purchase price; it is regularly lower.
Source: Perini's own brokerage practice under § 34i GewO · as of 10.09.2026
The top of the range requires correspondingly strong income — foreign-currency income included; incidental purchase costs come from own funds where the borrower lives abroad. Equity up to 40 % depending on the case, plus incidental costs.
Many lenders cap non-residents internally at 50 or 60 % — that is one bank's number, not the market's. Foreign-currency income and the banks that accept it.
Equity requirements: down payment and purchase costs
The down payment plus the purchase costs (roughly 8–15%), which are normally paid from equity.
Budget your own funds for both the down payment and purchase costs. Which German banks finance non-residents?.
What if the bank values the property below the purchase price?
The bank bases the loan on its own valuation. If this is below your purchase price, you receive a smaller loan and must pay the difference from your own funds.
When valuation and purchase price match, the calculation is straightforward. A lower valuation means a smaller loan and more cash for the difference, in addition to purchase costs. See the income currencies we place on the non-resident page.
Purchase price — Valuation = price: €400,000; Valuation 10 % below price: €400,000.
Bank valuation — Valuation = price: €400,000; Valuation 10 % below price: €360,000.
Loan at 80 % (example) — Valuation = price: €320,000; Valuation 10 % below price: €288,000.
Cash needed for the price — Valuation = price: €80,000; Valuation 10 % below price: €112,000.
Purchase costs (transfer tax, notary, registry, agent) — Valuation = price: on top, assumed paid from equity in this example.
Why do some lenders stop at 50 or 60 %?
Most lenders impose an internal limit for non-residents, often 50 or 60 %. Some do not lend to non-residents at all. A high equity requirement from your German bank therefore reflects that bank’s rules, rather than the options available across the market.
Our work is to find lenders that handle non-residents as regular clients. We discuss which banks fit your circumstances individually rather than list them on the website.
Which five factors influence the loan-to-value?
We assess the property, income type, country of residence, purpose and completeness of the documents. These five factors influence your loan-to-value.
- The property. A marketable residential property in a sound location: the best starting point. Special-purpose properties, very rural locations or properties with a renovation backlog push down the bank’s valuation — and with it the loan amount.
- The type of income. Permanent employment is simpler than self-employment; income in euros simpler than in a foreign currency. Both are feasible; it decides the choice of bank.
- The country of residence. An EU residence is less complicated than a third country. But Dubai, Singapore, the USA and Switzerland are everyday business too — with more documentation.
- The purpose. Owner-occupation, buy-to-let or a later return to Germany — banks assess these differently.
- Complete documents. The most mundane and most effective lever. A complete application gets better terms than the same case in fragments.
What purchase costs must you fund separately?
In addition to your down payment, budget separately for purchase costs. Non-residents often underestimate this second block.
Property transfer tax (3.5 % to 6.5 % depending on the federal state), notary and land registry fees, and any estate agent commission typically add up to 8–15 % of the purchase price — and that amount has to come from your own funds regardless of the loan-to-value ratio, because banks will not finance it.
On a €400,000 purchase at an illustrative 80 % loan-to-value (within the 60–100 % range), that means: on top of the €80,000 in equity from the lending calculation, a further €32,000 to €60,000 in purchase costs needs to be available separately.
Separate the down payment and purchase costs from the start. This avoids a common cross-border surprise: a mortgage offer that looks workable but requires more equity than you budgeted.
Which block is larger depends heavily on the federal state and whether an estate agent is involved. Check both before making an offer.
Model calculations without guarantee. Not binding offers. Terms vary depending on credit profile, property and bank. No tax or legal advice.
Frequently asked questions
What sets the loan-to-value in your case?
A mortgage in Germany is possible even if you are resident abroad. The lending limit is 60 to 100 % of the mortgage lending value, depending on the type of income and credit rating; the basis is the bank's valuation, not the purchase price.
The country of residence determines the pool of banks, not the range. The acquisition costs (additional purchase costs) come from your own funds.
How much equity do I need?
You'll need the down payment itself plus the purchase costs, roughly 8–15%, since lenders won't finance those. Plan equity for both.
Why does my German bank quote a loan-to-value of only 50 or 60 % for non-residents?
Most lenders set an internal cap for non-residents, often at 50 or 60 %. Your bank’s high equity requirement tells you about its own policy, rather than what the whole market can offer.
Any questions on this topic?
A first consultation is free and without obligation — the commission is, as a rule, paid by the bank. We tell you what this means for your own financing.
For a property loan, most banks only arrive at a workable calculation from a household net income of around €3,500 a month — for couples, the joint income counts.
Share the property price, any existing valuation and the cash available after purchase costs. We can assess a realistic loan-to-value figure for your German purchase from abroad.
Related pages
Non-residents: the overview
Buy a house in Germany while living abroad: which banks lend to non-residents, how much equity is needed and what documents are required.
How long it takes
Mortgage process in Germany: usually 3 to 10 working days from a complete file to approval — and what slows it down for non-residents.
Foreign-currency income and the banks that accept it
Foreign currency mortgage in Germany: how banks apply a safety discount to CHF, USD or GBP salaries, which discounts are typical and who lends.
Buy to let mortgage in Germany: how much will banks lend to non-residents?
For non-resident buy-to-let, limited tax liability in Germany is the prerequisite. Involve tax advisers in both countries — we do not provide tax advice.
Mortgage rates Germany: what do expats and non-residents pay?
A German mortgage rate consists of a market reference — driven by capital-market conditions no bank controls — and the individual margin the lender adds.
Buy a house in Germany from Dubai: do German banks lend to UAE residents?
The UAE’s removal from the EU risk list has clearly improved banks’ willingness to lend. A residence permit in Germany is one factor among several the bank weighs, not a blocker on its own.
Mortgage affordability calculator: how much can you borrow in Germany?
From payment, interest rate and initial repayment rate it derives the maximum loan; combined with your equity, that gives the financeable total.
Mortgage amortization calculator: how much is left when your fixed rate ends?
Mortgage amortization calculator for a German loan: monthly instalment, remaining balance and term — including the effect of annual extra repayments.
Country of residence: which ones rule out a German mortgage, and why
Country of residence and a German mortgage: sanctions, source of funds, payment traffic and document form decide — four points you can check in advance.
Buying German property with a Dutch or Austrian residence
Buying a property in Germany with a Dutch or Austrian residence: euro income without a currency discount, equity up to 40 % plus purchase costs.
Buying German property from the USA or Canada: who will finance it?
Buying German property from the USA or Canada: USD/CAD income at 6 to 10 specialist banks, FATCA, source of funds and power of attorney with apostille.
Buying property in Germany from the USA, UK and Asia: which banks lend?
Buying property in Germany from the USA, UK and Asia: 60–100 % loan-to-value, up to 40 % equity plus costs, FATCA and substitute evidence without SCHUFA.

Editorially responsible: Olga Nikushkina — owner, §34i GewO (German mortgage brokerage), adviser register D-W-132-ZUCB-95. Specialised in German property financing with an international dimension: non-residents, foreign-currency income, cross-border workers, expats. Siegfried Perini is entered in the German intermediary register under this licence as a person directly involved in brokerage and advice (§ 11a GewO), active in real estate since 1992. Not legal or tax advice.